
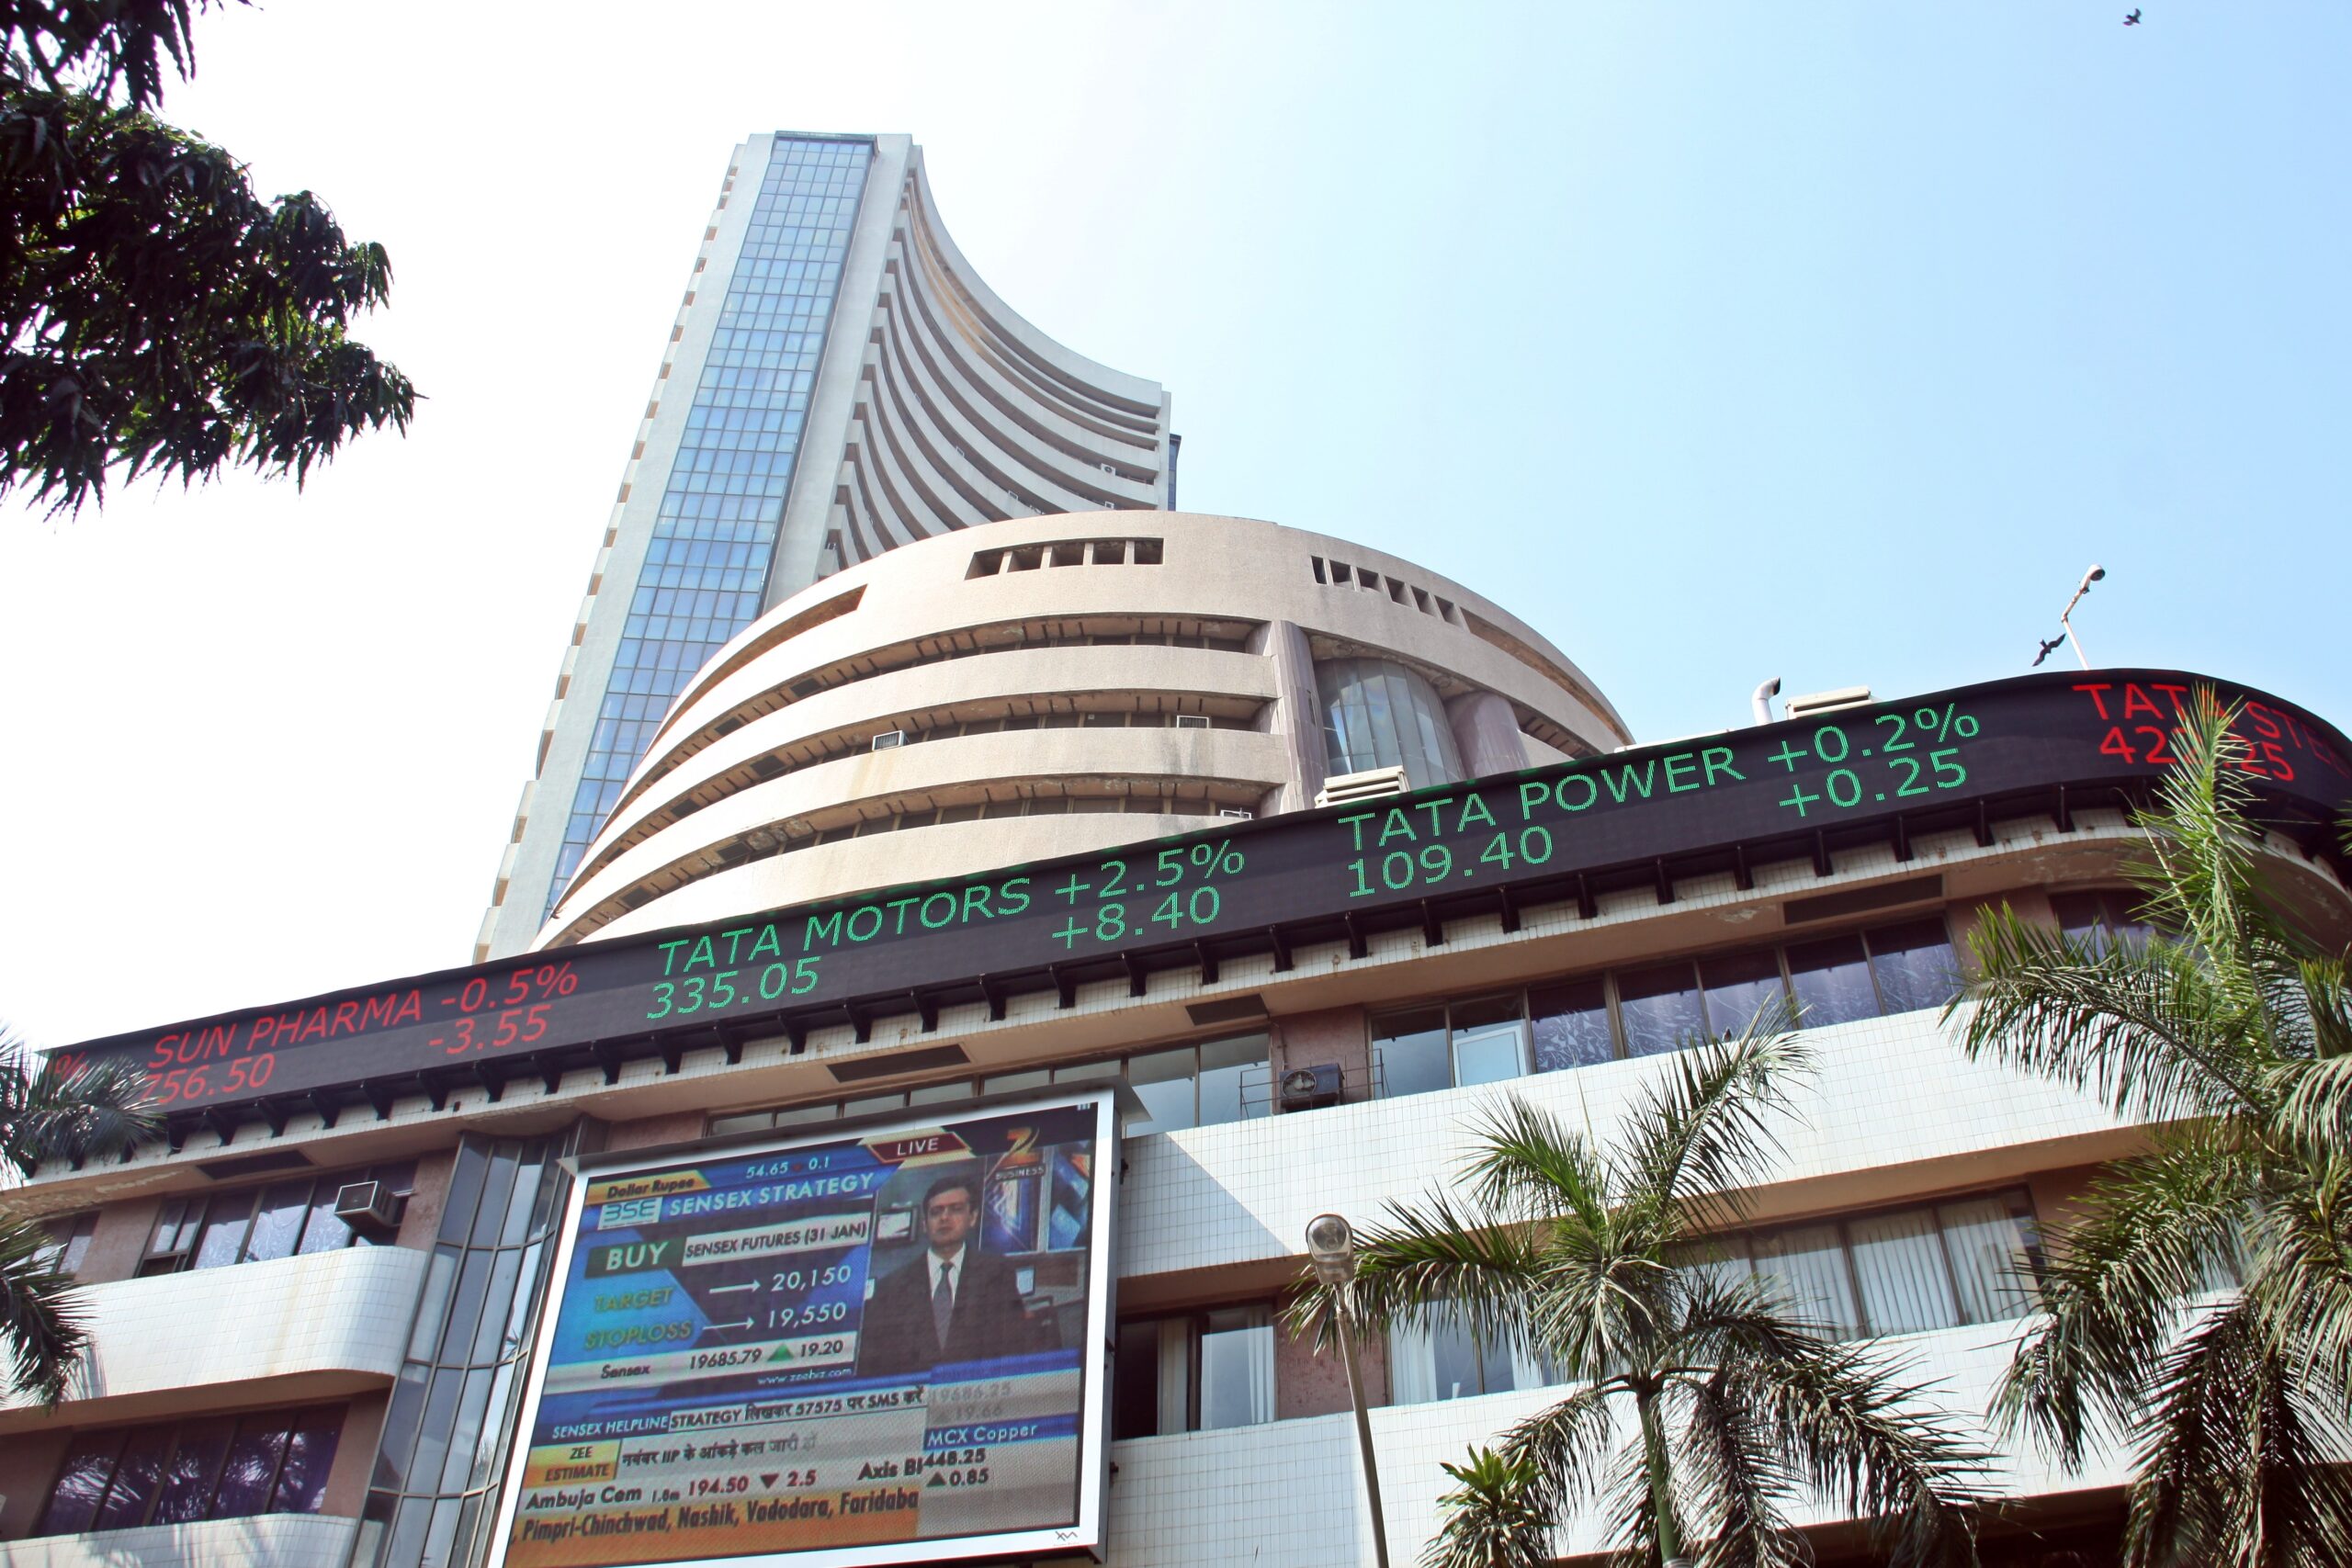
Subheading: Private banks account for about 65% of primary market activity, but losing the 35% contribution from public sector banks is a cause of concern
On most market days, an initial public offering (IPO) operates like a carefully choreographed relay race. Investors place their bids, banks block the requisite funds, registrars reconcile applications, shares are allotted, and stock exchanges prepare for listing.
However, if bank branches across India close for three consecutive days, the primary market suddenly finds itself waiting at the handover point.
The Banking Bottleneck: High-Speed Bidding Meets Slow-Motion Back-End Settlement
A proposed nationwide bank strike spanning three consecutive days (28th to 30th September), compounded by the second Saturday and Sunday bank holidays, creates an effective five-day disruption to branch-based banking operations. Making matters more complex, the disruption overlaps with the half-yearly closing of banks on September 30, a period when treasury operations, accounting processes, and interbank reconciliations already face heightened workloads.
The immediate concern for the primary market is not whether digital payment channels like UPI or mobile banking will stop functioning. Rather, the question is whether the vital back-end machinery—fund blocking, bid validation, refund processing, demat share credits, and final exchange approvals—can maintain its customary timeline.
The Digital Front-End vs. Back-End Banking Infrastructure
India’s primary market has accelerated significantly in recent years, transitioning from paper applications to ASBA (Application Supported by Blocked Amount) and UPI mandates. Yet, despite front-end digital accessibility, the post-issue pipeline remains deeply reliant on sequential institutional processing:
Investor Places Bid via UPI/ASBA ⟶ Bank Validates & Blocks Funds
Registrars Reconcile Allotment ⟵ Exchange Consolidates Bids
Shares Credited & Funds Unblocked ⟶ Final Exchange Listing
As market participants note, digital accessibility at the front end does not automatically ensure instantaneous back-end settlement.
“The primary market’s front end is modern and digital, but its spine is still connected to traditional clearing and reconciliation channels. When those back-end nodes slow down, even for operational reasons, the entire listing calendar has to stretch,” said Mr Arun Kejriwal, a veteran Capital Markets & Regulatory Policy Analyst.
Issues in the Interruption Zone
At least nine public issues – spanning mainboard offerings and SME listings – have active bidding or post-issue processing schedules overlapping this potential disruption window:
| Issue | Segment | Issue close date | Why it may matter |
| Moneyview Ltd | Mainboard | September 28 | Closure falls on the first day of the proposed strike |
| A-One Steels India Ltd | Mainboard | September 28 | Bank-linked processing could be affected |
| Orient Cables (India) Ltd | Mainboard | September 29 | Closure falls during the strike |
| German Green Steel and Power Ltd | Mainboard | September 29 | Allotment and reconciliation may need rescheduling |
| Runwal Enterprises Ltd | Mainboard | September 29 | Listing calendar may move if post-issue processing is delayed |
| AceVector Ltd | Mainboard | September 29 | Large retail participation could increase reconciliation pressure |
| Bench Mark Infotech Services Ltd | SME | September 29 | SME issues can also face banking and registrar dependencies |
| Himalayan Solar Ltd | SME | September 29 | Closure overlaps with the disruption |
| Green Asia Impex Ltd | SME | September 28 | Issue closure coincides with the first strike day |
Subscription levels recorded prior to the disruption, such as Moneyview at 4.73 times, German Green Steel at 1.48 times, and Orient Cables at 1.32 times, highlight the substantial volume of funds and bid data requiring swift reconciliation across multiple intermediaries.
These subscription figures should not be interpreted as final outcomes. They are a snapshot and can change before closure. However, they illustrate the scale of activity that exchanges, banks and registrars may need to process during a compressed period.
Other public IPO calendars also showed issues such as SRIT India and Shah Investor’s Home scheduled to open around September 28, while Nityas Gems & Jewellery was shown as opening on September 30. These dates should be treated as indicative until confirmed through the issuer’s offer documents and exchange filings.
Operational Risk vs. Fundamental Value
To understand how this affects retail participants, consider the journey of an applicant placing a ₹2 lakh bid via a UPI mandate on the final day of an issue.
While the application appears instantly submitted on the investor’s smartphone screen, the underlying funds remain blocked in the banking system while registrars verify duplicate bids, confirm bank approvals, and prepare the basis of allotment.
Investor Submits UPI Application
▼───────────────────────────────────────▼
Digital Front-End Back-End Banking Nodes
• Immediate Bid Submission • Multi-day Fund Blocking
• Online Confirmation Received • Manual/Batch Reconciliation
• App shows “Success” status • Delayed Allotment & Refunds
Merchant bankers view this stoppage by public sector banks as an unhealthy and counterproductive situation for primary market operations.
“A public sector bank strike lasting three days will definitely have a negative impact on primary market operations and investor expectations simultaneously,” noted Mr. Nikunj Mittal, Chairman & Managing Director, NNM Securities Pvt Ltd. “Of course, private banks account for about 65% of primary market activity, but losing the 35% contribution from public sector banks is a major setback for primary market operations.”
As we know, as the bank operations face back-end delays, funds remain blocked longer than usual, and listing schedules shift.
Under Securities and Exchange Board of India (SEBI) guidelines, issuers possess clear regulatory mechanisms to manage force-majeure events or banking strikes, including the ability to extend the bidding period by at least three working days. Furthermore, regulations specify compensation of ₹100 per day for delayed unblocking of application money beyond prescribed timelines, ensuring retail capital remains protected.
Strategic Takeaway for Issuers and Investors
The convergence of a multi-day bank closure, half-yearly accounting periods, and a dense IPO calendar illustrates a key structural lesson for India’s capital markets.
For issuers and lead managers, operational flexibility and clear market disclosures are critical. For retail investors, the primary guidance is to focus on official stock exchange circulars rather than speculative updates, recognizing that temporary operational delays do not diminish underlying corporate fundamentals. While India’s primary market infrastructure continues to digitize rapidly, its ultimate speed remains bound to the operational rhythm of its banking framework.

Leave a Reply