
- Q2 FY27 Total Income at ₹208.97 Crore, up 132% YoY,
- H1 FY27 Total Income grows 136% to ₹365.95 Crore,
- Cupid Raises FY27 Guidance to ₹880+ Crore Revenue and ₹275+ Crore Net Profit; FY28 Guidance to ₹1,305+ Crore Revenue and ~₹390 Crore Net Profit; FY29 Guidance to ₹1,950+ Crore Revenue and ~₹605 Crore Net Profit
Mumbai: Cupid Limited (“Cupid” or “the Company”) (BSE: 530843 | NSE: CUPID), Bharat’s rapidly growing consumer wellness and personal care company with a strong global healthcare franchise, announced its unaudited financial results for the quarter and half year ended 30th September, 2026.
Key Consolidated Financial Highlights:
Key Financial Highlights – Q2 FY27:
- Total Income of ₹208.97 Cr, YoY growth of 132% and QoQ growth of 33%.
- Operating Income of ₹187.86 Cr, YoY growth of 122% and QoQ growth of 21%.
- EBITDA of ₹54.77 Cr, with an EBITDA Margin of 29%.
- Profit Before Tax (PBT) of ₹72.89 Cr, YoY growth of 126% and QoQ growth of 22%.
- Net Profit of ₹56.22 Cr, YoY growth of 133% and QoQ growth of 27%.
- Net Profit Margin of 30%, up 135 bps YoY.
Key Financial Highlights – H1 FY27:
- Total Income of ₹365.95 Cr, YoY growth of 136%.
- Operating Income of ₹342.58 Cr, YoY growth of 137%.
- EBITDA of ₹114.83 Cr, YoY growth of 156%.
- Profit Before Tax (PBT) of ₹132.81 Cr, YoY growth of 157%.
- Net Profit of ₹100.37 Cr, YoY growth of 156%.
- Net Profit Margin of 29%, up 217 bps YoY.
Note: Operating income is revenue from operations. Percentage figures are rounded off to the nearest whole number.
Q2 & H1 FY27 Highlights
- Q2 FY27 total income stood at ₹208.97 Cr, registering growth of 132% YoY and 33% QoQ.
- H1 FY27 total income increased 136% YoY to ₹365.95 Cr, while net profit grew 156% to ₹100.37 Cr.
- The domestic business contributed ₹224.64 Cr, accounting for 67% of H1 FY27 sales compared with 41% in FY26, led by the Consumer Healthcare & FMCG business at ₹166.88 Cr (49% of sales), reflecting the growing scale and contribution of the Company’s consumer portfolio.
- The international business contributed ₹112.73 Cr, representing 33% of H1 FY27 sales, supported by institutional demand through the PFSCM agreement and supplies under South Africa’s 2025–30 national programme. The price revisions implemented across the export portfolio were reflected in realisations for the full H1 FY27.
- H1 FY27 EBITDA stood at ₹114.83 Cr, registering growth of 156% YoY. The Company continues to focus on strengthening its product mix, sourcing efficiencies and scale benefits as its Consumer Healthcare & FMCG business expands across organised retail channels.
- H2 FY27 is expected to be significantly stronger than H1, as the Palava facility is commissioned in Q3 FY27 and adds manufacturing capacity, and supplies to V2 Retail’s 425+ stores begin alongside the growing Style Baazar network.
Management Commentary
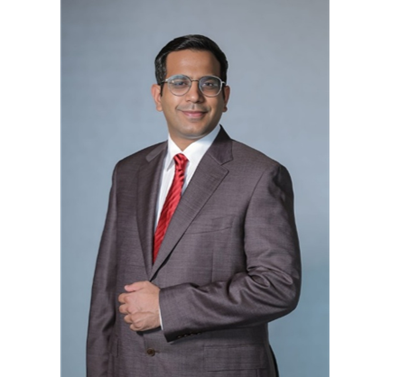
Commenting on the performance, Mr. Aditya Kumar Halwasiya, Chairman & Managing Director, Cupid Limited, said: “Our H1 FY27 performance reflects the growing scale of our business, with operating income increasing 137% to ₹342.58 crore and net profit growing 156% to ₹100.37 crore. Our domestic business contributed ₹224.64 crore, accounting for 67% of H1 sales compared with 41% in FY26, highlighting its increasing contribution to the Company’s growth.
Our international healthcare business continues to benefit from institutional demand through the PFSCM agreement and South Africa’s national programme. Price revisions across our export portfolio have also supported realisations, while we remain focused on strengthening our global partnerships and market presence.
In Bharat, our consumer business is expanding through organised retail partnerships. Our products will be available across 290+ Style Baazar stores, with an expected FY27 contribution of approximately ₹200 crore. Our exclusive partnership with V2 Retail provides dedicated retail space across 425+ stores, with an expected revenue contribution of approximately ₹400 crore over the next 12 months. We are also focused on improving sourcing efficiencies and leveraging distribution scale as the business expands.
On the manufacturing front, the Palava facility is scheduled for commissioning in Q3 FY27 and will take our annual production capacity to approximately 1.25 billion male condoms and 125 million female condoms at full capacity. Its dual-polymer capabilities will further strengthen production flexibility and support our international growth plans. Closer home, we are evaluating a medical-devices manufacturing project in West Bengal, which would further broaden our healthcare manufacturing base.
Value retail is an important marketplace for us. Cupid Limited’s FMCG portfolio is grossly under-penetrated in India, and with our associations with V2 Retail and Style Baazar, we as a company are well placed to capitalise on this opportunity for our FMCG business.
Supporting our manufacturing business is our association in South Africa, which, like other countries, is looking to reduce its import bill by offering incentives for local production. As an associate with up to 49% equity ownership, Cupid stands to benefit from this. In addition, our investment in GII will help us cement relationships across the Middle East. These three strategies are unique to Cupid Limited and will synergistically drive volumes while maintaining favourable margins. Multiple further associations are also being worked upon.
We expect H2 FY27 to be significantly stronger than H1. Palava commissioning in Q3 will add meaningful manufacturing capacity, and our partnerships with V2 Retail and Style Baazar will start contributing to revenue at scale. Backed by this visibility, we have raised our FY27 guidance to at least ₹880 crore in revenue and ₹275 crore+ in net profit. We have also revised our guidance upwards to at least ₹1,305 crore in revenue and approximately ₹390 crore in net profit for FY28, and at least ₹1,950 crore in revenue and approximately ₹605 crore in net profit for FY29. We will make the Company debt-free as we go along.”



Leave a Reply